Historical opinion essay: The complete corrected manuscript retained by the account, including its personal argument, is preserved below. The original byline and publication date remain unverified. Its financial, entrepreneurial, and gambling examples are the manuscript’s thought experiments and opinions, not investment or business advice.
(Note: The original version of this article contained an obvious error in the probability calculation for the taxi’s colour. This corrected version is being republished, with a few other revisions as well. I sincerely apologize for any inconvenience caused by the earlier version being shared.)
“I began to wonder what secondary things I should give up so that I could concentrate on pursuing what mattered most. And, ultimately, only one thing mattered most to me: being with you.” — André Gorz
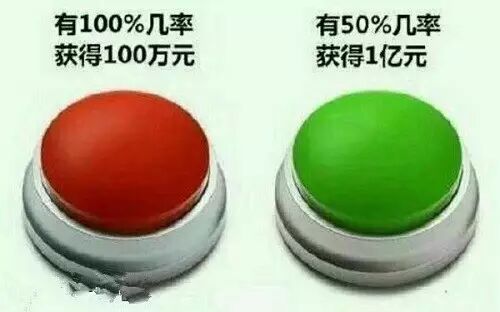
As shown above, a “simple” multiple-choice question: would you press the red button or the green one?
This question is more interesting than it seems. Let me try to answer it:
1. According to expected-value theory, the green button is worth 50 million;
2. Many people would still prefer a guaranteed one million, because they cannot bear a 50% chance of getting nothing;
3. In other words, if someone cannot tolerate “having nothing,” the choice on the right is equivalent to “a 50% chance of receiving 100 million and a 50% chance of dying.” Of course you cannot tolerate death, especially with a probability as high as 50%;
4. Thinking more openly, if you own the right to make this choice, you could sell the option on the right, with an expected value of 50 million, to someone able to bear the risk—for 20 million, for example, or even more;
5. To improve on the previous idea and increase the chance of finding someone willing to buy the option, you could sell it for just one million—a low upfront payment—but require the buyer to share the proceeds with you if they win 100 million;
6. Going further, you could turn the option into a publicly issued lottery, splitting it into retail tickets: two units of currency per ticket, with 200 million tickets printed and a top prize of 100 million. Compared with option 5, the risk is lower and the return higher;
7. Given the success of the business model in option 6, start raising the next 100-million jackpot and turn it into a business;
8. Using a price-to-earnings valuation, raise two billion, take the business public, and reach a market capitalization of ten billion.
From one million to ten billion: let us examine the mathematics behind it.
Economics has three concepts concerning decisions under risk: expected value, expected utility, and prospect theory.
Expected value: In probability theory and statistics, the expected value of a discrete random variable—also called its mathematical expectation or mean, or simply expectation—is the sum of each possible outcome multiplied by its probability. In other words, it is the average corresponding to the “expectation” obtained by repeating a random experiment many times under the same conditions. (From Wikipedia.)
For example, the expected number obtained by rolling a six-sided die is 3.5, calculated as follows:
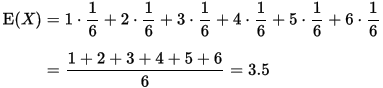
Expected utility: In microeconomics, game theory, and decision theory, expected utility is a utility theory in which individuals making choices under risk seek to maximize expected utility, rather than necessarily maximizing expected monetary value. This hypothesis is used to explain decisions in gambling and insurance. (The concept arose to address the “St. Petersburg paradox.”)
Prospect theory: In the 1970s, Kahneman and Tversky systematically studied prospect theory. Mainstream economics had long assumed that everyone makes decisions “rationally,” but reality is otherwise. Prospect theory incorporates asymmetric psychological utility associated with gains, losses, and the relative likelihood of outcomes, successfully explaining many phenomena that appear irrational.
Building on these theories, I would like to explore several interesting topics:
1. The counterintuitive practice of “making every decision according to the probabilities that optimize the overall outcome” is the first secret of successful people in the conventional sense;
2. Poor people sell their “probability rights” cheaply to rich people. These rights represent a more concealed and larger-scale extraction of surplus value—although this does not mean I endorse the concept of surplus value;
3. Today’s much-discussed artificial intelligence, such as AlphaGo, combines neural networks and search methods to evaluate positions and choose the next move; this does not mean its successive moves are probabilistically independent;
4. Yet irrationality and impulse may become humanity’s last stronghold. (I will write about this separately later.)
Let us first go through the basic concepts.
Expected-value theory: A wise person’s basic decision-making tool
According to expected-value theory, a 100% chance of receiving 50 million and a 50% chance of receiving 100 million with a 50% chance of receiving nothing have the same expected monetary value, but not the same risk or utility.
The weighted calculation of expected value is one of the simple tools that decision-makers frequently use. Bayes’ theorem instead updates conditional probabilities in light of new evidence; the taxi example below involves that kind of update.
An explanation: “Multiply the probability of a loss by the amount that might be lost, then multiply the probability of a gain by the amount that might be gained, and finally subtract the former from the latter. This is the method we have always tried to use. It is not perfect, but it really is that simple.” (Attributed to Buffett.)
Example A: From the memoir of Rubin, former CEO of Goldman Sachs
“After the two companies announced their merger, shares in Wuniweisi traded at $30.50, compared with $24.50 before the announcement.
That meant that if the merger went through, the share price could rise by $3 through the arbitrage trade, because each Wuniweisi share would be worth $33.50: 0.6075 times the price of a Beidi share.
If the merger failed, Wuniweisi shares might fall back to approximately $24.50 each. The shares we bought could therefore fall by about $6.
We estimated the probability of the merger succeeding at approximately 85%, and the probability of failure at 15%. In expected-value terms, the potential increase in the share price was $3 multiplied by 85%, while the downside risk was $6 multiplied by 15%.
$3 × 85% = a potential gain of $2.55
−$6 × 15% = a potential loss of −$0.90
Therefore, expected value = $1.65.
This $1.65 was the return we hoped to earn by committing $30.50 of the firm’s capital for three months. That gave a potential return of 5.5%, or 22% on a simple annualized basis. Our minimum acceptable return was a little below that. We did not consider it worthwhile to commit our firm’s capital for an annual return below 20%.”
Rubin explained in particular that this was what he did every day. It looks like gambling, and indeed often results in losses. But what he needed to ensure was making money most of the time.
Example B: From the author of The Black Swan
At an investment seminar, Taleb said, “I believe the market has a high probability of rising slightly next week—about a 70% chance.” Yet he sold large amounts of S&P 500 futures short, betting that the market would fall. His view was that a rise was more likely—“I am bullish on the market”—but shorting was the better choice—“I am bearish on the outcome”—because if the market did fall, the decline might be large.
The analysis is as follows. Suppose the market has a 70% chance of rising next week and a 30% chance of falling. But if it rises, it gains only 1%, whereas a fall could be 10%. The expected result is 70% × 1% + 30% × (−10%) = −2.3%. Under this simplified assumption, the expected return from shorting is positive. That does not mean the probability of making a profit is greater, and the calculation excludes costs and the actual risks of shorting.
As Munger said, Buffett spends every day doing this simple mathematical calculation. It is less a mathematical ability than a way of thinking. Understanding it is easy; putting it into practice is extremely difficult.
Probability sometimes seems “counterintuitive.”
Example C:
A taxi was involved in a crash on a rainy night. An eyewitness said the taxi was blue. We know that: (1) the eyewitness can distinguish blue and green taxis with 80% accuracy; and (2) 85% of the taxis in the area are green and 15% are blue. What is the probability that the taxi involved in the crash was blue?
Answer: The probability of a green taxi being seen as blue is 0.85 × 0.2; the probability of a blue taxi being seen as blue is 0.15 × 0.8. Therefore, the probability that the taxi really was blue is (0.15 × 0.8) / [(0.85 × 0.2) + (0.15 × 0.8)] = 41.38%. That is, the taxi is more likely to have been green.
Does that differ somewhat from your intuition? The way our brains work is astonishing, but in some aspects of mathematical intuition they are surprisingly inexperienced.
Yet expected-value theory cannot explain why many people still choose the red button even when it is worth only one million.
Expected-utility theory: Ambition or fear
In his 1738 paper, Daniel Bernoulli used the concept of utility to challenge the use of expected monetary value as a decision criterion. The paper principally presented two ideas:
a. Diminishing marginal utility: More wealth is preferable to less, so the first derivative of the utility function is positive. As wealth increases, however, satisfaction increases at a diminishing rate, so the second derivative of the utility function is negative.
b. Maximum utility: Under risk and uncertainty, the criterion for individual decisions is maximizing expected utility rather than expected monetary value.
Return to the example at the beginning. Choosing the red button means immediately receiving one million and giving up an option with an expected value of 50 million. One reason is being “satisfied with” one million: relative to one’s existing wealth, it already makes a difference of an order of magnitude, while another order of magnitude may be unimaginable. Another reason is avoiding the green button’s 50% risk of getting nothing. The fear of ending up with nothing far outweighs the prospect of another 49 million.
More precisely, choosing the red button reflects the combined effects of expected-utility theory and prospect theory.
Prospect theory
The book Do Not Be a Normal Fool quotes the following summary by Kahneman, who received the Nobel Prize for prospect theory:
a. When facing gains, people are risk-averse;
b. When facing losses, rational people are risk-averse, while “normal fools” are risk-seeking;
c. Rational decision-makers’ judgments of gains and losses are not affected by a reference point, whereas “normal fools” often judge gains and losses relative to one. For example, a rational decision-maker does not insist on waiting to break even before selling a stock that should be sold;
d. Normal fools are generally loss-averse.
As behavioural economics examines, social, cognitive, and emotional factors can lead people to make less “rational” choices.
For example, the amount of wealth one already has serves as a reference point and largely determines whether one presses the red or green button.
There are exceptions, too.
Zuckerberg came from a middle-class family. Yet, during a difficult period two years after his company was founded, he rejected Yahoo’s $1-billion acquisition offer.
Would you take one billion immediately, or accept a probability of just a few percent of receiving 100 billion several years later? The choice facing Zuckerberg resembles the button choice at the beginning of this article. By comparison, his green button—the penalty for losing—was much harsher.
Several years later, Snapchat similarly rejected Zuckerberg’s $3-billion acquisition offer.
This is one aspect of the Silicon Valley spirit. A dream of getting rich alone can hardly drive an enterprise of great ambition.
Their attitudes toward wealth, their ambitions, and their youth led them to press a green button with a probability of success far below 50%.
I once chatted with a man who said that what we lack most, in fact, is a father who tells us that we are damn good.
Why do scholarly or wealthy families produce so many accomplished people? Apart from genes and resources, the following factors may also play a role:
1. A sufficiently high reference point: They are not lured away by small gains and can better bear risks, even when success has a low probability, thereby capturing high returns;
2. The example set by the people around them;
3. Inner motivation that has been ignited.
They are less likely than ordinary people to sell off their probability rights “cheaply.”
Abandoned probability rights
1. At key decision points in the divide between rich and poor, “poor people” give up their own probability-based opportunities;
2. The secret of so-called winners is to keep acting on favourable probabilities, maintaining their principles for life’s wagers even after repeated setbacks;
3. Buying lottery tickets is the most expensive form of abandoning one’s rights over probabilistic choices, which is why it is called paying a “fool’s tax.”
Invest in value when you have a lot of money, but take a gamble when you have little. This may be the most widely practised foolishness in investing.
Low-probability things are hard to achieve but may look easy. High-probability things may seem a long way off, yet they offer a much greater chance of reaching the destination.
Giving up one’s probability rights and choosing a comfortable low-probability option means using already meagre resources to subsidize the “successful.”
Why can’t intelligent people win the game?
If life is a game of probabilities, and our successive choices determine its eventual outcome, intelligent people would seem to have an “innate advantage.” But that is not actually the case.
Probability emerged from gambling. Pascal and Fermat’s interest in its curious outcomes led them to propose principles that helped establish probability theory.
Take blackjack, a casino game offering players a relatively high probability of “not losing.” The secrets of making money are:
1. Choose a “friendly” casino—the equivalent of choosing the right industry;
2. Know the basic rules and techniques inside out;
3. Count cards, as in the film 21;
4. Increase your bets when the probabilities are in your favour;
5. Regardless of the outcome, follow these strategies consistently, without emotional fluctuations.
Intelligent people can do steps 1–4 well.
But step 5, which goes “against human nature,” is a weakness for many intelligent people.
In a casino, you face all kinds of distractions: there may be no place available at the best moment to bet; the gambler next to you may be smoking; a woman’s cleavage may catch your eye; and you may feel anxious or afraid.
Google’s technical team and professional Go players jointly studied the games between AlphaGo and Lee Sedol. These records offer a glimpse of how artificial intelligence “thinks” while playing this exceptionally difficult intellectual game.
On each move, AlphaGo combines the current board position, a policy network, a value network, and tree search to estimate the prospects of winning and select a move. It seeks favourable decisions, but successive moves are not independent: they depend on the preceding position and possible continuations.
Rubin, Taleb, and Buffett, discussed earlier, are almost like human AlphaGos: they persist in acting according to probabilities, often in ways that seem “counterintuitive, contrary to human nature, and uncomfortable.”
The vast majority of intelligent people have not yet acquired that wisdom or that remarkable way of acting.
Fools who pay the lottery’s “fool’s tax” and intelligent people who understand probability but cannot consistently put it into practice both remain trapped by the same thing: desire.
In the face of intense desire, intelligent people believe their luck will improve their odds. Less intelligent people believe diligence will compensate for their shortcomings.
Successful people certainly work hard, but hard work is not a sufficient condition for success. Successful people are the outcome of a selection process, and explanations for their success are attributed after the fact.
There is therefore another tax more concealed than the “fool’s tax”: the “get-rich-dream tax.”
This may explain two common “economic phenomena”:
1. Why do commercial streets in China constantly undergo renovation and changes of tenants, while businesses abroad comparatively seldom change?
2. Why are so many Taobao shop owners willing to work diligently around the clock for an income lower than a salary?
The high rents paid by frequently changing street-front businesses, and online entrepreneurs’ efforts without regard for returns, are premiums paid for the dream of getting rich.
How can you avoid selling your options too cheaply?
Many of life’s multiple-choice questions offer an “other” option in addition to A, B, C, and D.
To tackle the Germans’ cipher machine, Turing and his colleagues used machine-assisted codebreaking. In 1941, Turing, Welchman, Alexander, and Milner-Barry jointly wrote to Churchill requesting additional staff and resources, and received his support. The manuscript’s dramatized detail of “Turing writing alone and securing £100,000” should not be presented as historical fact.
Being able to press either the red or the green button means I have a choice. Could there be another way to realize its value?
A third path—selling the option to venture-capital or private-equity investors—uses capital’s appetite and capacity for risk to share in the value between one million and 50 million.
Interestingly, the world of wealth leaves a hidden doorway for young people with nothing. Their desire for one million does not have to mean losing the opportunity for 50 million. All they need is a wider perspective.
This is one of the principal forces driving the creation and distribution of wealth in today’s society. It is also part of the beauty of capital.
Your way of thinking and acting when deciding what to do with an “option” determines your eventual place in the financial food chain.
Life’s choices are limited
Life offers many moments of choice. We cannot always be driven by “probability” and “optimality.”
In Master and Commander, Captain Jack temporarily gives up pursuing an enemy ship and chooses to stop at an island to fulfil the ship’s surgeon’s longed-for Darwin-style scientific exploration.
I am reminded of a friend whose family postponed starting a business and buying a home to spend time with their growing child.
Many beautiful things and beautiful moments arise from choices made “without calculation.”
André Gorz said, “I began to wonder what secondary things I should give up so that I could concentrate on pursuing what mattered most. And, ultimately, only one thing mattered most to me: being with you.”
Of course, it would be best if we held enough chips, won using an AlphaGo-style calculation of probabilities, to spend as we wish or to help those without the right to enter life’s casino—for example, through a charitable foundation like Gates’s.
Perhaps choice itself matters more than wealth. If time is the most precious wealth, what of the choices in life that are even more limited than time?
I remember going to Guangzhou alone after graduating in 1995. I met a mentor who saw in me a certain intuitive aptitude and generously praised me in front of others as “a young genius.” Time always favours the young over the old; no one has yet called me a middle-aged genius.
When registering his company, he struggled to choose a name. Then he said, “Why not call it ‘Choice’?”
That became the first company I joined. Its name carries a broad metaphor for life:
“Choice Limited.”
Editorial note
During migration, the taxi calculation already corrected in the manuscript (41.38%) was retained, while minimum clarifications distinguished expected value, expected utility, Bayesian updating, and the probability of profit. The claim that each AlphaGo move is independent was corrected using the original paper; the dramatized account of Turing’s letter was corrected using the letter held by the UK National Archives. The remaining views on life, business, and society are the historical manuscript’s opinions and have not been revalidated as universal rules.
Supporting references
Silver et al.: Original AlphaGo neural-network and tree-search paper (2016)
The UK National Archives: 1941 letter to Churchill from Turing and three colleagues
Sources and editorial history
Restored from a complete historical article exported from the PhDSciNet Official Account.
Editorial revision: During migration, the taxi calculation already corrected in the manuscript (41.38%) was retained, while minimum clarifications distinguished expected value, expected utility, Bayesian updating, and the probability of profit. The claim that each AlphaGo move is independent was corrected using the original paper; the dramatized account of Turing’s letter was corrected using the letter held by the UK National Archives. The remaining views on life, business, and society are the historical manuscript’s opinions and have not been revalidated as universal rules.